B2B remittance forms the backbone of international trade, allowing businesses to execute cross-border transactions seamlessly. It involves transferring large amounts of funds between businesses, often across different countries. This article explores the mechanisms of B2B remittance, its importance in global commerce, and how technological innovations are enhancing this essential financial service efficiently and securely.
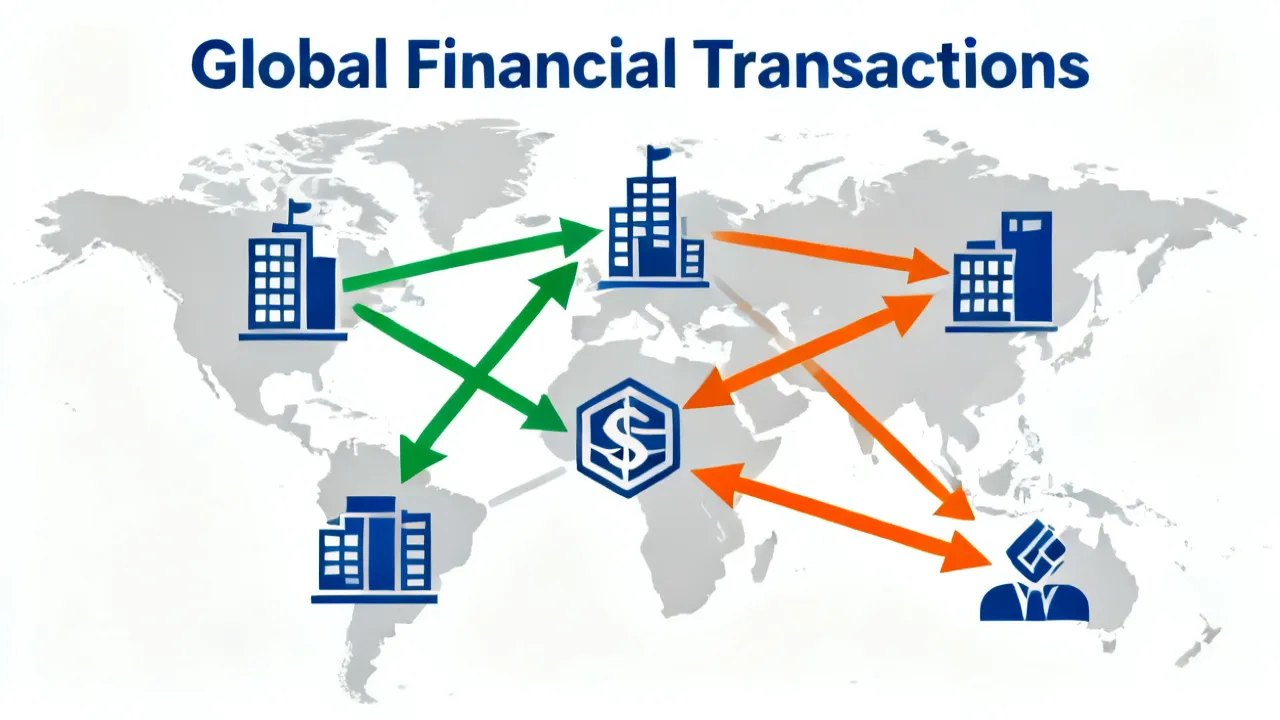
In the realm of international trade and commerce, B2B (Business-to-Business) remittance is a pivotal element that enables businesses to engage in financial transactions across borders smoothly. This financial service forms the bedrock of global trade, facilitating the transfer of substantial sums of money between companies, ensuring that transactions are executed seamlessly despite the geographical divide. The efficiency of B2B remittance impacts the liquidity of supply chains, influences procurement strategies, and ultimately affects a company's ability to seize new market opportunities.
B2B remittance involves the execution of transactions between businesses, where funds are transferred from one organization's bank account to another. Traditionally, this was done through banks, which are still vital players in the ecosystem. However, in recent years, fintech innovations have revolutionized the way businesses manage these transactions. The process typically begins with the initiating company instructing its bank to transfer funds to a supplier's bank account. This involves intermediary banks or payment processors that help facilitate the transaction, especially when dealing with different currencies.
Several modern B2B remittance solutions utilize electronic platforms that offer speed, transparency, and security, enhancing overall efficiency. These platforms help eliminate the complexity often associated with international transactions, such as currency exchange and compliance with regulatory requirements by leveraging technology for automatic validation and processing. Furthermore, these systems can provide real-time tracking and reporting, allowing businesses to manage cash flows effectively and strategically plan their finances.
One of the crucial aspects of B2B remittance is the establishment of reliable suppliers. Businesses need to ensure that their suppliers, who often operate from different countries, are credible. This assurance forms a significant part of the risk management strategy, ensuring that goods are paid for, shipped, and delivered in time, thus maintaining the supply chain's integrity. The loss of trust in a supplier can lead to interruptions in production or supply, translating into financial losses and damaged reputations.
To build relationships with reliable suppliers, businesses should conduct thorough due diligence and risk assessments that encompass financial stability checks and reviews of the supplier’s operational practices. Suppliers should also demonstrate their compliance with international standards and regulations, which protects businesses from potential legal repercussions and enhances their supply chain reliability.
The advent of blockchain technology and cryptocurrencies has brought about significant changes in B2B remittance. Blockchain ensures that transactions are secure and transparent, while cryptocurrencies offer an alternative to traditional currency exchanges by eliminating intermediaries, thereby lowering transaction costs and time delays. The decentralization of transactions through blockchain is not only enhancing security but also providing unprecedented levels of transparency in the payment process.
Moreover, businesses can utilize smart contracts—self-executing contracts with the agreement directly written into code on the blockchain. These transactions automatically execute and validate when certain conditions are met, reducing human error and operational costs. Companies engaging in international trade can leverage these technologies to streamline payments, mitigate risks associated with currency fluctuations, and reduce the need for extensive reconciliation processes.
| Aspect | Traditional Solutions | Modern Solutions |
|---|---|---|
| Speed | Several days | Fast to a few hours |
| Transparency | Limited | High (e.g., blockchain) |
| Costs | High transfer fees | Reduced fees with digital currencies |
| Security | Moderate | Enhanced with advanced technologies |
Implementing a B2B remittance system requires strategic planning and execution. Here is a step-by-step guide to facilitate integration:
For successful B2B remittance, businesses must adhere to several conditions:
To better understand the transformative impact of modern B2B remittance solutions, it’s useful to look at real-world examples of companies that have successfully integrated these innovative systems into their operations.
A mid-sized tech firm with international suppliers made the decision to shift from traditional bank transfers to blockchain-based payments. The company faced significant delays and high transaction fees using conventional methods, especially when sending payments to suppliers in countries with weaker banking systems.
Upon implementing a blockchain platform, transaction speeds improved dramatically. Payments began processing in hours rather than days, allowing the company to maintain adequate inventory levels and build stronger relationships with suppliers. Additionally, the transparency of blockchain technology reduced disputes regarding payment statuses and helped the firm maintain better compliance with international regulations.
An e-commerce company found itself challenged by high transfer fees due to the diverse array of payment systems its international suppliers used. This significantly impacted their profit margins. To resolve this issue, the company teamed up with a fintech provider offering a tailored B2B remittance solution that allowed for bulk payment processing.
This collaboration not only slashed transaction costs by over 30% but also streamlined the payment process, enabling the e-commerce firm to expand its operations and explore new markets without the stress of financial transaction bottlenecks. Their ability to pay suppliers promptly improved vendor trust and led to more favorable terms, enhancing their overall competitive edge.
What are the benefits of using modern B2B remittance solutions?
Modern solutions offer increased speed and transparency, reduced costs, and enhanced security through advanced technologies like blockchain. Furthermore, the predictive analytics these platforms provide can help businesses in financial forecasting, allowing better cash flow management.
How does blockchain impact B2B remittance?
Blockchain ensures transaction security and provides a transparent ledger for all parties, making audits easier and more reliable. Moreover, blockchain's decentralized nature minimizes the reliance on intermediaries, leading to more efficient transactions.
What factors should I consider when selecting a B2B remittance provider?
Consider transaction fees, speed, global reach, regulatory compliance, the technology used for processing transactions, and how well they integrate with existing systems. Additionally, assess the provider's reputation and customer service quality, as these factors will contribute to the overall effectiveness of your remittance process.
B2B remittance is an indispensable service for businesses engaged in international trade. As technological innovations continue to advance, the complexity and cost associated with these transactions show promising reductions, granting businesses more agility and confidence to expand their global operations. Looking ahead, businesses that adapt quickly to these advancements will not only survive but thrive in an increasingly interconnected global economy.
As we look to the future, it is clear that B2B remittance will continue to evolve in response to technological innovations, changing economic landscapes, and shifting customer expectations. Key trends are beginning to emerge that will shape the future world of B2B remittance.
Artificial intelligence (AI) is set to redefine B2B remittance processes. By employing advanced algorithms, AI can analyze transaction data to detect irregularities, reducing the likelihood of fraud. AI can also facilitate predictive analytics, allowing businesses to forecast cash flow needs accurately and optimize payment schedules based on supplier reliability.
With globalization fueling an explosion in cross-border e-commerce, the demand for seamless B2B remittance solutions is anticipated to soar. Companies engaged in e-commerce will require faster, more efficient ways to pay suppliers and manage international transactions as online shopping platforms expand their reach into diverse markets.
As the B2B remittance environment grows, regulatory requirements will concurrently become more stringent. Businesses must stay proactive in complying with regulations such as the General Data Protection Regulation (GDPR) in the EU or similar measures in other jurisdictions. This focus on regulatory compliance will necessitate cooperation between remittance service providers and businesses to ensure secure data handling and privacy standards are upheld.
With increasing consumer awareness, companies are under pressure to demonstrate their commitment to corporate social responsibility. B2B remittance will need to adapt to support ethical practices, ensuring that supply chains are not only efficient but also socially responsible. This may involve selecting suppliers based on sustainability practices or implementing ethical sourcing initiatives.
As businesses adjust to these changes, they must remain vigilant in tracking industry trends and technological advancements in B2B remittance. Firms willing to innovate and embrace these changes will be in a stronger position to capitalize on new opportunities and mitigate the risks associated with international commerce.
In conclusion, B2B remittance is an essential component of global business operations, propelling companies toward successful international engagement. The transformative power of technology and the evolving landscape of regulations pose both challenges and opportunities. It is crucial for businesses to develop not only robust remittance frameworks but also to cultivate strong supplier relationships, maintain compliance, and leverage advancements such as blockchain and AI. In doing so, organizations can enhance their financial agility, bolster competitive advantage, and navigate the complexities inherent in a global marketplace effectively.
This guide explains how payroll teams typically access and configure Runpayroll.adp.com for reliable payroll processing. It provides objective background on why employee payroll portals matter, how authentication and permissions affect payroll controls, and what organizations should verify before running pay cycles. The focus remains on governance, accuracy, and operational readiness rather than marketing claims.
This guide explains how Runpayroll.adp.com fits into payroll operations, from setup to ongoing compliance and reporting. Background information covers why payroll portals matter, what organizations typically configure, and how an expert approach evaluates security, controls, and workflow. Readers will also find a comparison of onboarding paths, key conditions, and practical FAQs.
This guide reviews what people discuss on Justworks Reddit to help HR and small-business leaders evaluate payroll, benefits, and admin workflows objectively. The article summarizes common themes, explains what readers should verify, and offers a structured way to compare providers. Background context clarifies how community forums, vendor communications, and compliance realities shape user experiences.
This guide synthesizes what people commonly discuss in Justworks Reddit threads and turns it into practical, objective criteria for SMB decision-making. Background context is provided on what Justworks is, why HR/payroll conversations appear on Reddit, and how to evaluate providers without relying on hearsay or pricing rumors.
Kony DBX helps organizations plan, deploy, and optimize data handling for reliable application workflows. This guide explains what “Kony DBX” typically refers to in enterprise contexts, outlines selection and integration considerations, and offers practical steps and requirements. It also addresses governance, performance, and operational risks in an objective way, including an expert Q&A section for decision-makers.
This guide explains Kony Dbx in practical terms—how it fits into modern product workflows, what to evaluate when sourcing, and which conditions typically matter before purchase. Objectively, “DBX” concepts often relate to signal/processing or equipment configuration layers, while “Kony Dbx” is commonly used as a product/series name in procurement discussions.
This guide explains what Kony DBX is, how it fits into deployment workflows, and what to evaluate when choosing units or integrating suppliers. Objectively, it covers typical hardware/software considerations, procurement criteria, and operational requirements. It also includes a comparison table, a practical step-by-step checklist, and expert FAQs—helping you make defensible decisions for reliability, compliance, and maintainability.
Cash Management Services for Corporates help firms centralize liquidity, streamline payments, and improve visibility across banking relationships. This guide provides objective background on cash management, key service capabilities, and typical procurement considerations, focusing on corporate treasury needs such as payment controls, forecasting support, and operational governance.